
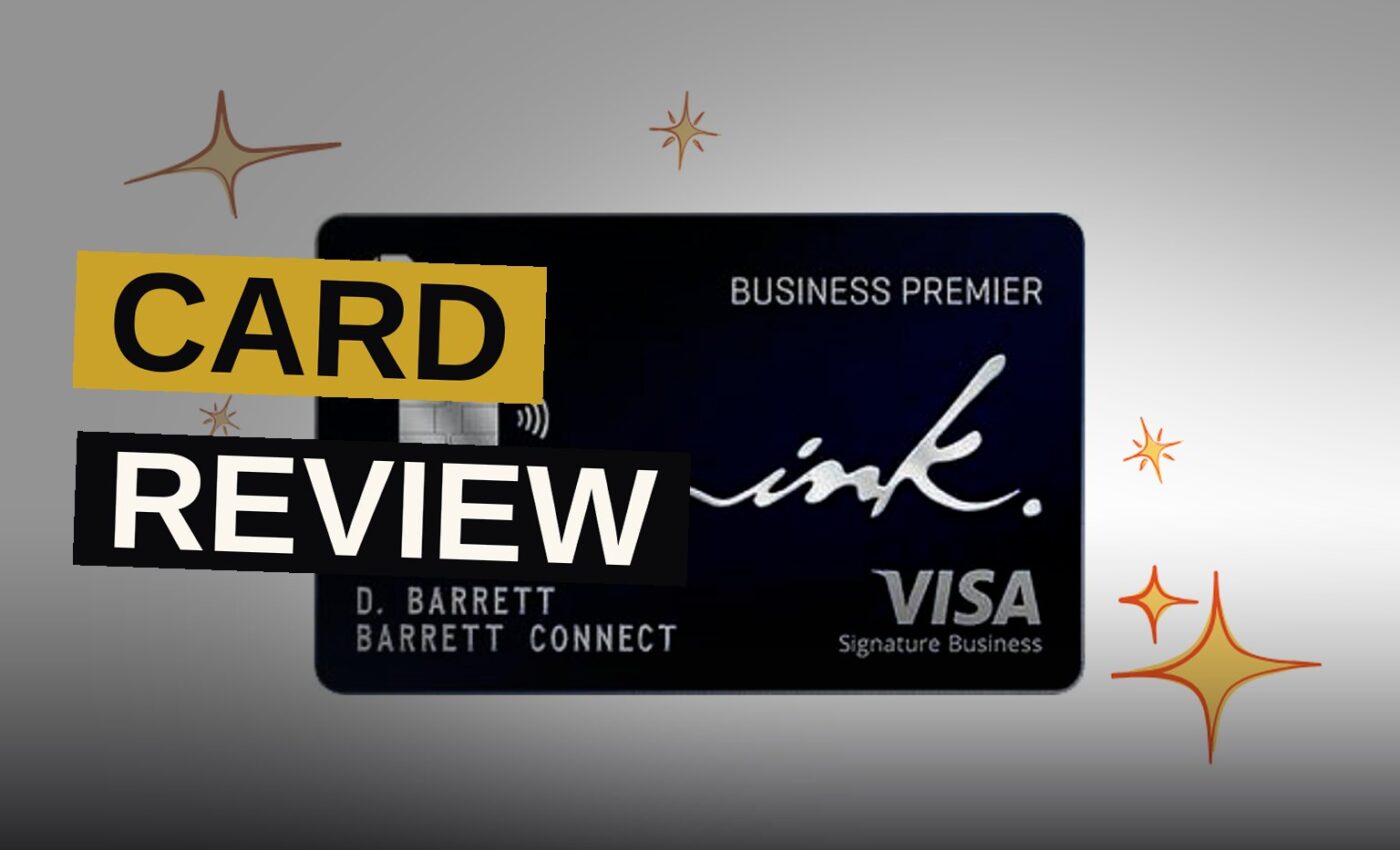
The Ink Business Premier Credit Card is a cash-back workhorse for business owners who spend heavily and want rewards without juggling bonus categories. It offers unlimited 2% cash back on everyday purchases, a higher rate on big-ticket items, and free employee cards. The trade-off is a $195 annual fee and a pay-in-full structure that demands steady cash flow.
The card’s headline feature is its welcome bonus: earn $1,000 bonus cash back after spending $10,000 in the first three months. That spending requirement is steep, but for businesses that move that volume anyway, the bonus lands quickly. Rewards never expire, and there is no minimum redemption amount when you cash out.
The rewards structure
The Ink Business Premier earns cash back at three different rates, depending on how you spend. The base rate is a flat 2% on all business purchases, which covers most routine expenses like supplies, software, and contractor payments.
Purchases of $5,000 or more earn 2.5% cash back. That is a 25% bonus over the standard earning power of the card. Chase rewards business owners who make large purchases with this elevated rate, though the source does not specify exactly how the rate applies to the transaction amount.
You also get 5% cash back on bookings made through Chase Travel℠. That rate applies to flights, hotels, cruises, and rental cars booked through the portal. There are no blackout dates for airfare booked through Chase Travel, and you can add your loyalty program numbers to reservations to earn rewards on the trip itself.
The $195 annual fee question
The annual fee is the card’s biggest hurdle. At the 2% base rate, you need to spend $9,750 per year just to cover the fee with rewards. That figure assumes you only earn at the base rate.
For high-spending businesses, the fee is easy to overcome. For smaller operations, it may not be worth it. The card also has no bonus categories, so there is no way to accelerate earnings beyond the large-purchase and travel rates.
One structural point matters here: the Ink Business Premier is primarily a pay-in-full card. You must pay off your monthly charges each statement period, though Chase offers a feature called Flex for Business that lets you carry a balance over time with interest. Not all purchases are eligible for that option, so you need the cash flow to clear the bill most months.
Employee cards and extra benefits
Adding employee cards costs nothing, and those cards earn the same cash-back rates as the primary card. You can set individual spending limits on each employee card to control risk. That makes the card a clean fit for teams that make purchasing decisions independently.
The card also bundles several protections that can justify part of the annual fee. Rental cars used for business purchases receive primary coverage against damage or theft.
Cell phone protection covers damage or theft up to $1,000 per claim, with a $100 deductible. It applies to all phones listed on your monthly bill, including employees’ phones, and allows up to three claims per 12-month period.
Purchase protection covers eligible new purchases against damage or theft for the first 120 days after the purchase date, with a $10,000 limit per item and $50,000 per account. Extended warranty protection adds one year to eligible U.S. manufacturer warranties of three years or less.
How to redeem your points
Cash back is tracked as points, and every 100 points equals $1. You can redeem for a statement credit to reduce your balance or a direct deposit to an eligible U.S. checking or savings account, with no minimum redemption amount.
Travel bookings through Chase Travel℠ are another option. You can cover some or all of a reservation with points, and there are no blackout dates for airfare. Gift cards are available from more than 150 retailers, restaurants, hotels, and other merchants, and you can give them away if you do not want them yourself.
| Redemption option | How it works | Minimum redemption |
|---|---|---|
| Cash back | Statement credit or direct deposit to U.S. bank account | None |
| Chase Travel℠ | Book flights, hotels, cruises, rental cars with points | None, subject to availability |
| Gift cards | Redeem from 150+ retailers and merchants | Not specified |
| Apple products | Pay for purchases through the Apple Ultimate Rewards Store | Not specified |
One limit stands out: you cannot transfer these points to Chase’s airline and hotel partners. That is a significant difference from other Chase Ultimate Rewards cards, where transfer partners are a major selling point. If you value flexibility to move points to airlines, this card will not give it to you.
Points do not expire as long as your account stays open and in good standing.
Referrals and a Lyft promotion
You can earn extra points by referring other businesses. When a referred business is approved, you receive 20,000 bonus points, up to 200,000 points per year. That maximum is equivalent to $2,000 in cash-back rewards.
There is a tax wrinkle: cardholders with successful referrals may receive a Form 1099 each year for the value of the referral bonus. That means the referral income is reportable, so factor that into your planning.
Lyft riders get a limited-time bonus. You earn 5% cash back on Lyft rides when you pay with the Ink Business Premier, and the promotion runs through March 2025.
Who should get this card
The Ink Business Premier is built for high-spending business owners who want cash back without tracking categories or activating offers. The flat 2% rate is simple, and the 2.5% large-purchase rate rewards the kind of spending that other cards cap or exclude.
You need the cash flow to handle a pay-in-full structure. Even with Flex for Business, the card is not designed for carrying balances month to month. If your business cycles through slow seasons, that is a real constraint.
The welcome bonus is generous, but the $10,000 spending requirement in three months is not trivial. If you cannot hit that number naturally, the bonus is not worth stretching for.
Pros and cons at a glance
- Generous welcome bonus of $1,000 after $10,000 in three months
- Unlimited 2% cash back, with 2.5% on purchases of $5,000 or more
- Free employee cards with individual spending limits
-
Primary rental car coverage, cell phone protection, and purchase protection included
-
High spending requirement to earn the welcome bonus
- $195 annual fee requires significant spend to overcome
- No bonus categories beyond the large-purchase and travel rates
- Pay-in-full structure limits flexibility for some businesses
The card also carries a caveat worth noting: all information about the Ink Business Premier Credit Card has been collected independently and is no longer available through Yahoo Finance.
For a business that spends consistently and wants straightforward cash back, the Ink Business Premier is a strong option. For a business that carries balances or spends lightly, the annual fee and pay-in-full structure make it a harder sell. Run your own numbers before you apply.
Source: finance.yahoo.com
Get the Notebook.
The day's best stories and every fresh verdict, in plain English, in your inbox by seven. One email a day, no more.